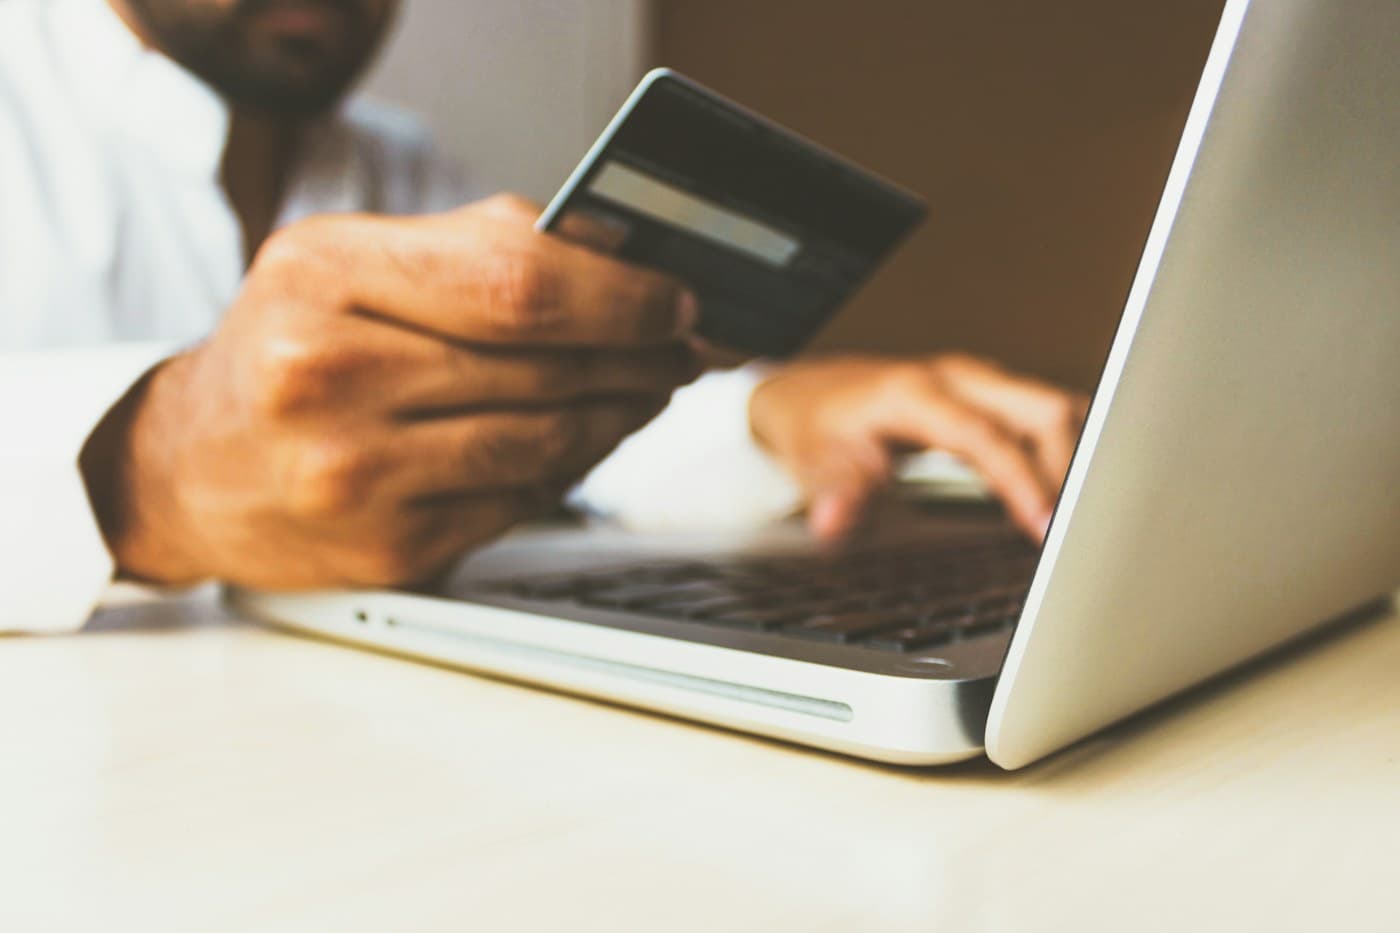
Reduce risk when a seller or offer looks tempting. Here is a practical way to think through the decision, one step at a time.
Understand the decision
A polished storefront can still be fraudulent. A low price, urgent countdown, or request to move payment to a private messaging app can be a warning sign.
What to compare
Check the seller’s history, return policy, contact details, secure checkout, and independent reviews. Avoid storing card details unnecessarily. Read the amount and recipient before confirming a payment.
A practical next step
Save the order confirmation and delivery promise. If goods do not arrive, contact the seller and payment provider through official channels promptly. Keep screenshots of the original listing.
Slow the transaction down
Fraud often depends on urgency. A caller may claim your account will be blocked, a refund will expire, or a family member needs immediate help. Pause and inspect the actual action on your screen. A payment request, QR code, link, or remote-access app can all move money or expose information. Use the official app or a contact number you found independently. Never share a PIN, OTP, or password to receive money. A legitimate problem will still exist after you take a minute to verify it.
Check the final screen
Before authorising a digital payment, read the recipient name, amount, and account or UPI details. Do not rely only on the label in a message or a sticker on a shop counter. For a new merchant, consider a small test transaction and confirm it arrived. Keep device and banking apps updated, use a strong screen lock, and enable alerts. Be careful with saved cards and public devices. The last screen before you enter a PIN is the most useful place to catch an error.
Know how to respond to trouble
If money leaves unexpectedly or you shared credentials, contact your bank or payment provider immediately through official channels. Ask to block the affected payment instrument or access and record the complaint number. Change passwords from a trusted device, preserve screenshots and transaction IDs, and check linked accounts. Reporting speed can matter under applicable rules, so do not wait until you understand the entire scam. Formal cybercrime and grievance channels can provide additional routes if the first response is inadequate.
Protect information between payments
Many attacks begin before a transaction: a fake KYC link, impersonated customer support, a malicious attachment, or a request to install screen-sharing software. Verify app publishers and web addresses, avoid entering banking details from a message link, and keep sensitive documents in secure storage. Do not grant remote control to a stranger who claims to fix a payment issue. Review alerts and statements regularly so a small test debit is noticed. Teach family members the same checks, especially anyone who may feel pressured by an authoritative call.
How to apply this to safer online shopping payments
Begin by writing the question in your own words: what decision are you trying to make, by when, and with whose money? For safer online shopping payments, use the three issues above as a first pass: understand the decision, what to compare, and a practical next step. Put the relevant statements, policy documents, or written quotes beside those questions. If an answer depends on a rate or rule, note where you verified it and the date of the source. This prevents a helpful general principle from turning into an outdated instruction. Write down the smallest action that would reduce uncertainty today, such as requesting a fee schedule or checking a balance.
A small working example
Imagine two households considering the same topic. One has stable income, no urgent debt, and a cash buffer. The other has variable income and a large bill due soon. Even if both read the same product description, the sensible next step can differ because their ability to wait, absorb loss, or make a fixed payment differs. Use your own numbers rather than copying a friend’s choice. List the best plausible outcome, a normal outcome, and a difficult outcome. If the difficult one would disrupt rent, food, or essential care, reduce the commitment or build a buffer first. This is especially useful when an offer is presented as a limited-time opportunity.
Questions to ask before deciding
Ask what the full cost is, how easily you can change course, and what information is missing. Check who provides the product or service and which official document controls the terms. Consider the impact on the next twelve months of cash flow, not just the first payment or a headline return. If the decision affects a partner or dependant, discuss the trade-off with them. It is reasonable to pause when an explanation relies on jargon you cannot translate into rupees and dates. Keep a record of the answer, the source, and any promise made in writing so you can revisit the decision later.
When to review the decision
Set a review point that matches the decision. A monthly budget may need attention after each pay cycle; a long-term investment or insurance policy may be reviewed less often, with an extra check after a major life change. Look for new facts: income, dependants, debt, product fees, regulations, and the date the money is needed. Do not change course merely because a headline is alarming or a neighbour chose something different. Return to the purpose you wrote down, compare it with the current facts, and make one deliberate adjustment at a time. If the issue crosses into tax or legal interpretation, seek qualified current advice.
A final check before you act
The most useful decision is the one you can explain and sustain. For safer online shopping payments, return to the key point: Verify the merchant and payment path before entering details. Write down the amount involved, the date by which you need an answer, and the document that confirms the current terms. Compare at least one realistic alternative and include fees, taxes, access, and the cost of being wrong. Share the plan with anyone affected by it. If an assumption changes, update the calculation rather than forcing the old choice to fit. Keep your emergency reserve and essential bills protected while you test a new approach. Small, well-understood steps give you clearer feedback than a large commitment made under pressure.
Keep the plan usable
Put your conclusion in a sentence that another person could understand. Note the figures you used and which of them are estimates. Check the current product document or official rule before a final payment or application. Set a reminder for the next review and keep a copy of the confirmation. If the decision has several moving parts, consider getting qualified advice and ask the adviser to explain the costs, assumptions, and alternatives in writing. A clear record helps you notice when circumstances change and prevents an old assumption from quietly becoming a permanent part of the plan.
Verify the merchant and payment path before entering details.
This article is for general education and is not personalised financial, tax, legal, or investment advice. Product terms and regulations may change; confirm current details with official sources or a qualified professional before acting.